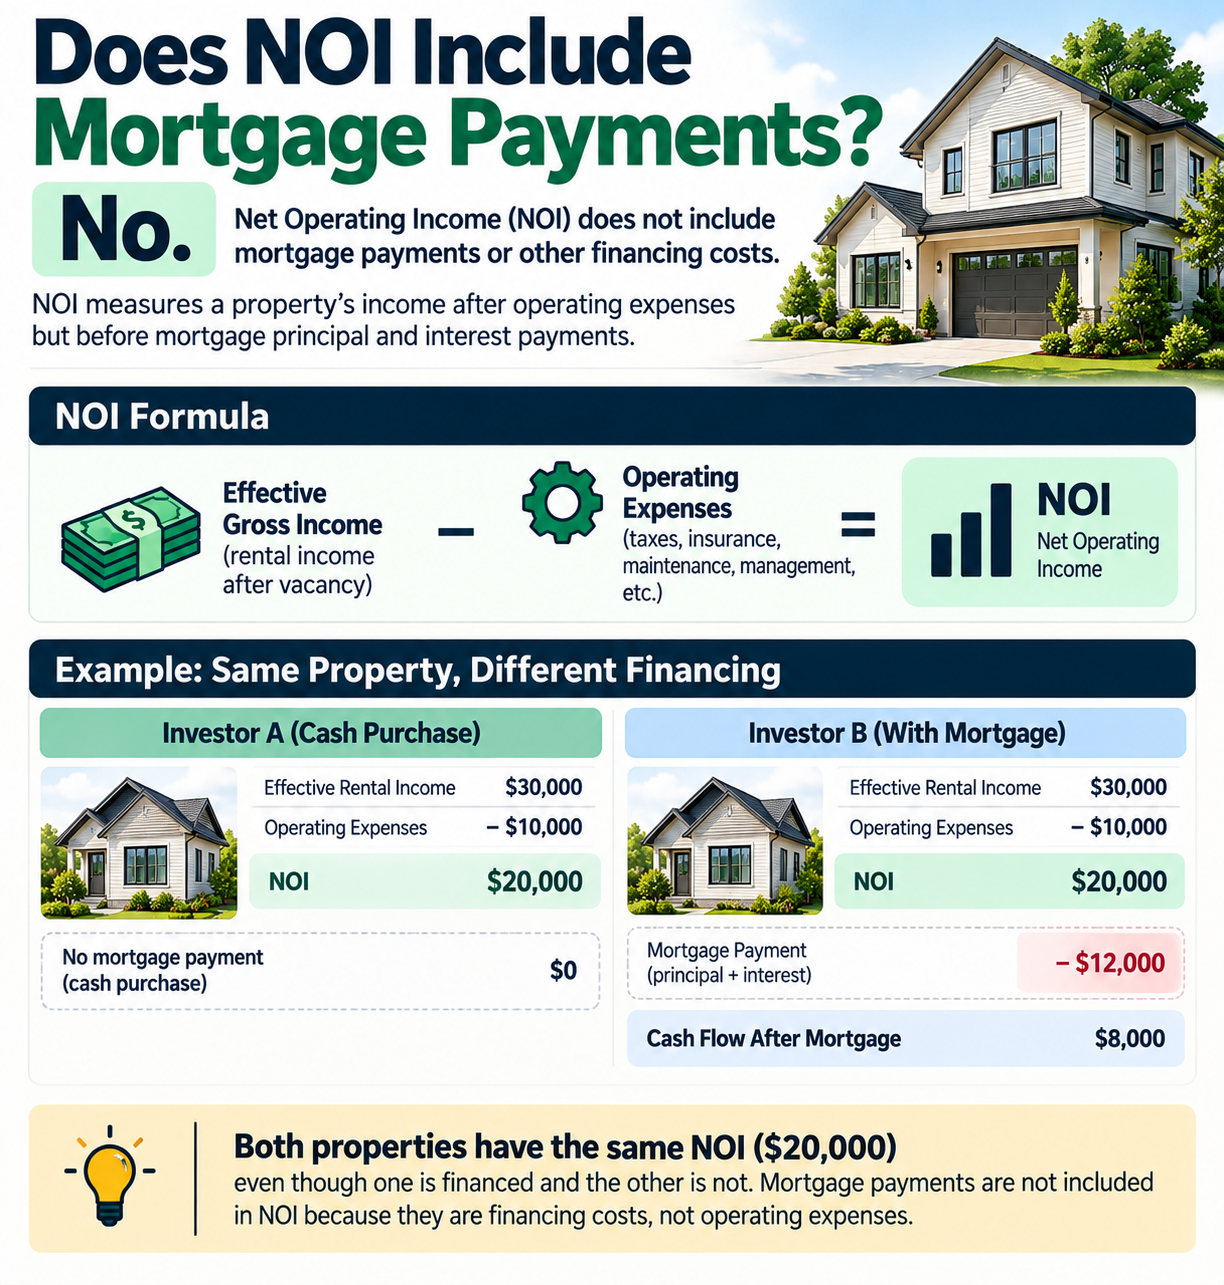
Does NOI include mortgage payments? No. Net Operating Income (NOI) generally does not include mortgage principal and interest payments or other financing costs.
NOI measures a property’s income after operating expenses but before mortgage principal and interest payments.
This distinction is important because two investors can own similar properties but use very different financing. By calculating NOI before financing costs, the property’s operating performance can be evaluated separately from how it is financed.
What Is NOI in Real Estate?
Net Operating Income is the income a property generates after subtracting its operating expenses from its effective gross income. It is commonly used when analyzing income-producing real estate.
NOI = Effective Gross Income − Operating Expenses
Operating expenses can include property taxes, insurance, maintenance, property management fees, and other costs required to operate the property. Mortgage payments are treated separately because they are financing costs rather than property operating expenses.
Does NOI Include Mortgage Payments?
No. Mortgage payments are generally not included when calculating NOI. This means both mortgage principal and mortgage interest are excluded from the NOI calculation.
NOI focuses on the property’s operations before financing. The mortgage depends on how the owner chooses to finance the property, while NOI is designed to measure income and operating expenses at the property level.
What Expenses Are Included in NOI?
Operating expenses used in an NOI calculation may include costs such as:
Property taxes • Property insurance • Repairs and maintenance • Property management fees • Utilities paid by the owner • HOA or association expenses when applicable • Other normal property operating expenses
The exact expenses can vary by property. The key question is whether the expense relates to operating the property rather than financing or the owner’s individual tax situation.
What Is Not Included in NOI?
NOI generally excludes mortgage principal and interest, other debt-service payments, income taxes, depreciation, and certain capital expenditures. These items may still matter when evaluating an investment, but they are normally analyzed separately from NOI.
For U.S. rental properties, mortgage interest may also have separate tax treatment, so it should not be confused with the operating expenses used to calculate NOI.
Why Is the Mortgage Excluded?
Imagine two investors buy similar rental properties with similar income and operating expenses. One investor pays cash, while the other uses a mortgage. Their financing costs are different, but the properties could still produce the same NOI.
Keeping mortgage payments outside NOI makes it easier to examine property operations separately from financing decisions.
NOI Example With a Mortgage
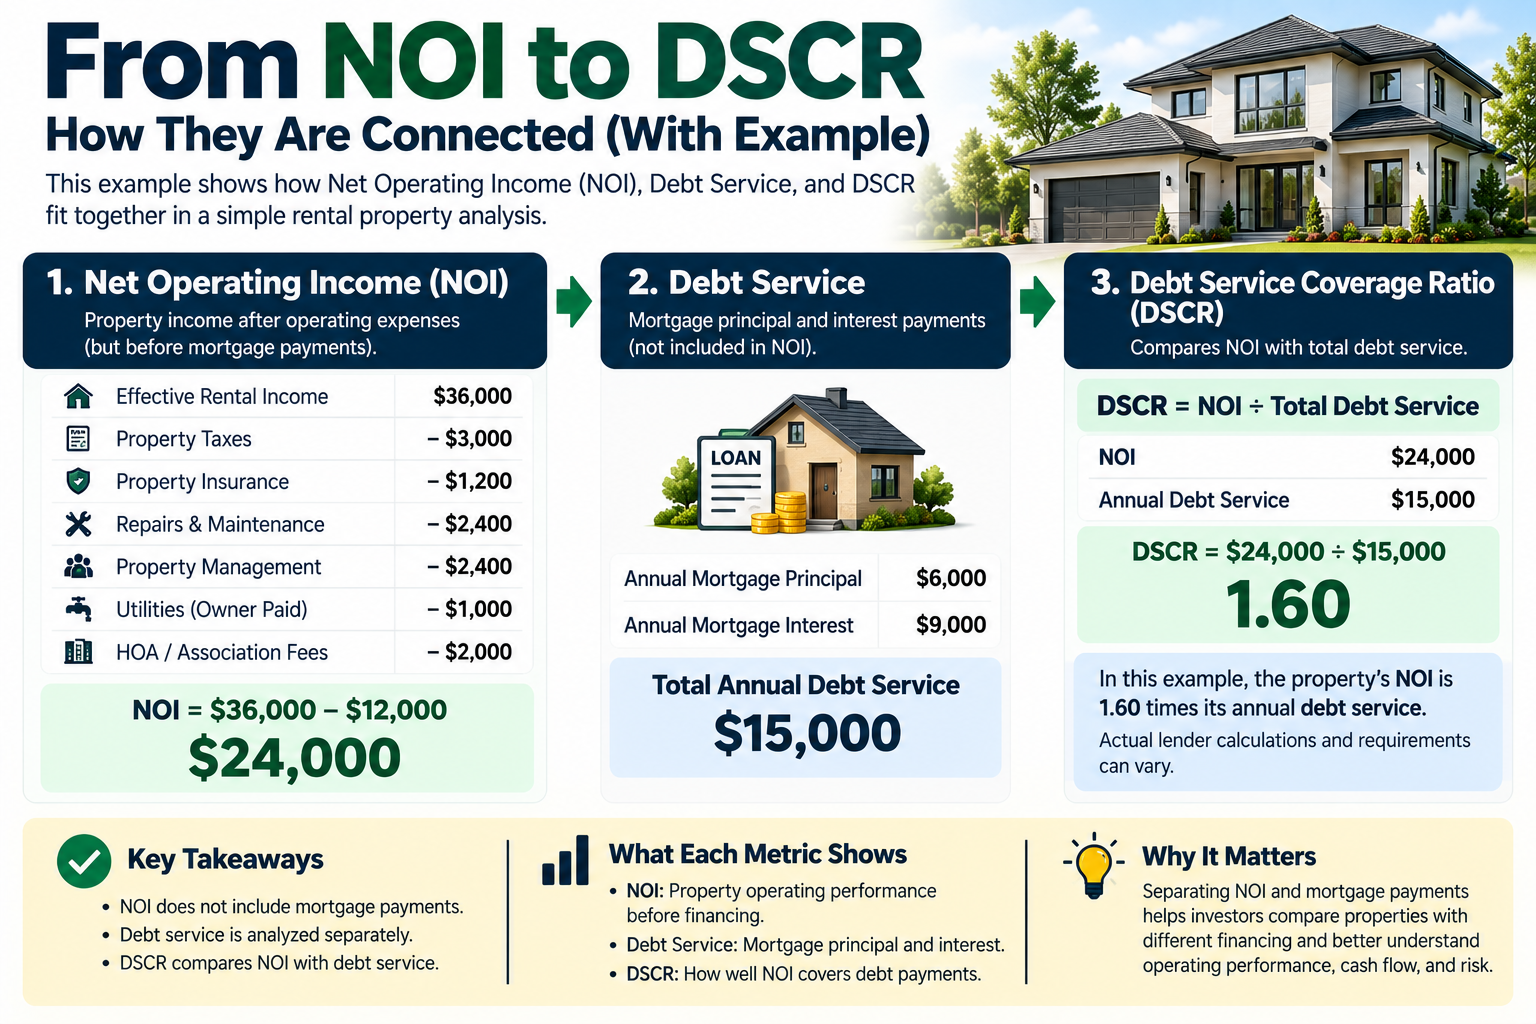
Suppose a rental property produces $36,000 in effective annual rental income and has $12,000 in annual operating expenses.
$36,000 − $12,000 = $24,000 NOI
Now suppose the owner also pays $15,000 per year in mortgage principal and interest. That mortgage payment does not reduce the property’s NOI. The NOI remains $24,000.
What Happens After the Mortgage Payment?
Although the mortgage does not affect NOI, it does affect the owner’s cash flow. In this simplified example:
$24,000 NOI − $15,000 Annual Debt Service = $9,000 Cash Flow Before Other Non-Operating Items
This is why NOI and cash flow should not be treated as the same number. NOI looks at property operations before financing, while cash flow can account for mortgage payments.
NOI vs Cash Flow
NOI and cash flow answer different questions. NOI helps show how the property performs before financing costs. Cash flow helps show how much money may remain after operating expenses and financing costs in a simplified property analysis.
For a deeper comparison, read our NOI vs Cash Flow guide.
NOI vs Debt Service
Debt service is the amount paid toward debt during a specific period. For a typical property mortgage, this can include principal and interest payments. Debt service is not deducted when calculating NOI.
Instead, NOI and debt service can be compared separately when analyzing whether a property’s operating income covers its debt payments.
How NOI Is Used in DSCR
Debt Service Coverage Ratio (DSCR) compares a property’s NOI with its debt service. A simplified formula is:
DSCR = NOI ÷ Total Debt Service
NOI: $24,000
Annual Debt Service: $15,000
DSCR: $24,000 ÷ $15,000 = 1.60
In this example, the property’s NOI is 1.60 times its annual debt service. Actual lender calculations and requirements can vary.
You can estimate this with our DSCR Calculator.
Why Separating NOI and Mortgage Payments Matters
Separating NOI from mortgage payments helps investors compare properties without allowing different financing structures to change the property’s operating-income calculation. Financing can then be analyzed separately through cash flow, DSCR, cash-on-cash return, and other measures.
For a complete explanation of Net Operating Income, read our What Is NOI in Real Estate guide.
Frequently Asked Questions
Does NOI include mortgage principal?
No. Mortgage principal payments are financing-related payments and are not deducted when calculating NOI.
Does NOI include mortgage interest?
No. Mortgage interest is also excluded from NOI. Both principal and interest are considered separately when analyzing financing.
Does NOI include property taxes?
Yes. Property taxes are generally included as operating expenses when calculating NOI.
Is NOI the same as profit?
Not exactly. NOI measures income after property operating expenses but before financing and certain other items. It does not represent an investor’s complete profit or investment return.
Can NOI be positive while cash flow is negative?
Yes. A property can have positive NOI but negative cash flow if its mortgage payments and other relevant cash outflows exceed the income remaining after operating expenses.
Final Thoughts
NOI does not include mortgage principal or interest payments. It measures a property’s operating performance before financing costs.
To understand a rental property’s financial picture, consider NOI alongside mortgage payments, cash flow, and DSCR rather than relying on one number alone.
Try our free NOI Calculator to estimate a property’s Net Operating Income.
Disclaimer: This article provides general educational information. Actual property calculations, lender methods, and financial circumstances may vary.